Solar PV Modules at Eighty Cents a Watt: Who's Still Making Money
TOPCon modules are quoted at RMB 0.82 per watt; tier-one makers bleed cash and tier-two plants idle lines. Our playbook: tier-one and near-tier-one brands only, EL testing on 3% of every batch, no stockpiling. Stocking 500 modules last October cost us RMB 20,000.
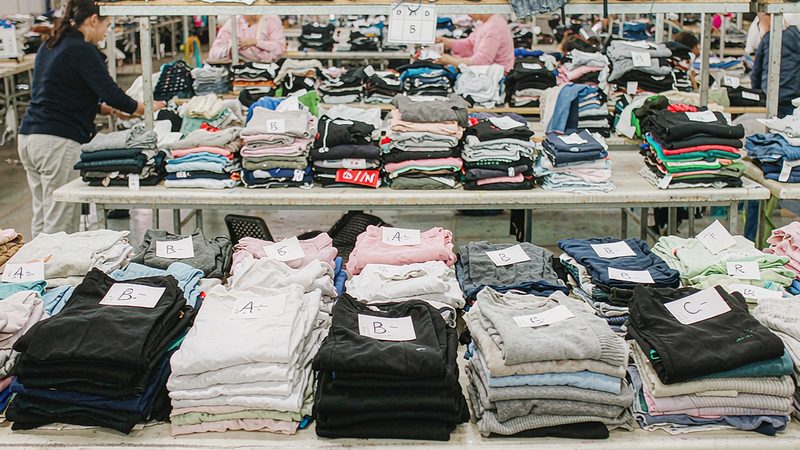
January 22nd, Changzhou solar warehouse. The supplier's sales rep sat across from me and pushed the quote over: TOPCon dual-glass, 580 watts, RMB 0.82 per watt.
Eight years in this business, I've watched modules fall from RMB 4.2 a watt to 0.8. Back in 2021, when polysilicon hit RMB 270,000 a ton, modules were 2.1 a watt, customers queued for stock, and full payment up front still meant waiting for production slots. Now polysilicon is just over 60,000, modules are below cost, and sales reps chase customers.
At the end of this month I quoted a Ghanaian customer 861 pieces of 580W modules at RMB 0.85 per watt, delivered to port. He replied with one line: "Are you even making money?" This piece is my answer.
How the Price Fell to Eighty Cents
Polysilicon capacity doubled in 2023, and new lines kept coming online in 2024. More material pushed wafers, cells, and modules down the whole chain, and nobody dares raise prices first.
Ex-factory prices at tier-one makers hit about RMB 0.85 in January, and tier-two and tier-three plants dared quote 0.80. Module makers' margin fell from RMB 0.20 a watt in 2021 to a few cents now.
At this level it's no longer competition — it's a shakeout. In the last two months of the year alone, I know of three small plants in sale talks.
Our Foshan warehouse still holds tail stock bought at last year's high prices — PERC, 550W, cost RMB 1.18, market price now 0.86. That batch shows a paper loss of over a hundred thousand. I look at the inventory sheet once a week and wince once a week. Expensive inventory and cheap market prices are the two knives hanging over every solar trader this year.
Tier One and Tier Two, Both Hurting
Tier-one makers hold on through scale and cash flow; they make their own polysilicon and can afford a while of losses. Their game is defending share — they ship even at low prices, because the day a line stops, workers and channels scatter.
Tier two has it hard. One Changzhou plant I've worked with idled a third of its capacity last December and rotated workers onto leave. Over dinner the boss told me: every watt shipped loses three fen, but not shipping loses more — rent and depreciation alone run RMB 80,000 a day.
He drank half a jin of baijiu that meal and asked me about next year's African market. I said I can't promise the market — just promise me quality. He laughed bitterly: at these prices, holding quality means picking the smallest loss.
Some small plants have started cutting specs. Frame aluminum thinned by 0.2 mm, encapsulant film swapped for cheaper stock — invisible to the eye. Last month I rejected a batch of 120 modules: uneven potting on the junction boxes, and they leaked on day three of the water immersion test. Freight and testing on that batch, RMB 8,400, came out of my pocket.
The day I rejected it, that plant's sales manager called me three times — "sis, take another two fen off the price and keep the goods." I told him it's not about the price, it's about the potting. A module shipped to Africa sits on a roof for twenty-five years; leaks burn the customer's power plant down.
How We Buy Now
These days I follow three rules on sourcing.
First: tier-one and near-tier-one only. When prices are low, the gap between big and small brands shrinks from fifteen fen to five — no reason to gamble. If a tier-one maker has a problem, they can afford the claim and you know where to find them.
Second: test every batch. Sample 3% for EL testing to catch microcracks, plus two pieces for water immersion. EL sampling runs RMB 1,200 a batch — tens of thousands a year, and it saves the freight of fighting over bad goods later.
Third: don't stockpile. Prices are still sliding, and inventory is a loss. We now buy against orders, payment terms stretched to 45 days, inventory under two weeks. Last October I stocked 500 modules; the price dropped four fen a watt in a month, a RMB 20,000 loss. Lesson learned.
There's one more rule not written down but always done: quote inverters and racking together with the modules. Module prices are transparent and earn nothing, but margin survives on inverters and racking. Bundled into one deal, gross margin holds at 8%. It's easier for the customer too — one container, everything included, install on arrival.
What's Changing on the Customer Side
Cheap is good for customers. That Ghanaian customer could only install 120 kW last year; this year the same money buys him 170 kW. His factory saves USD 1,100 a month on electricity.
An old customer in Kenya still hasn't finished installing the modules he stockpiled at 2021's high prices, and he slaps his thigh looking at eighty cents now. I told him to stop slapping — finish installing and start generating. Electricity generated is money.
But I put one thing up front: on a module at eighty cents, freight runs fifteen fen a watt and duties twenty — the module isn't the big line item. If you want the math, come to me and I'll lay out every landed cost line by line.
Can you make money at eighty cents? Yes — money from turnover, from inspection, from after-sales. Not from the spread. The ones chasing quick money all left this year.